Buying Off-Plan Property in Kenya: Questions to Ask Before You Commit
Evaluate an off-plan property by checking the developer, land, approvals, contract, payment milestones, specifications and handover process.
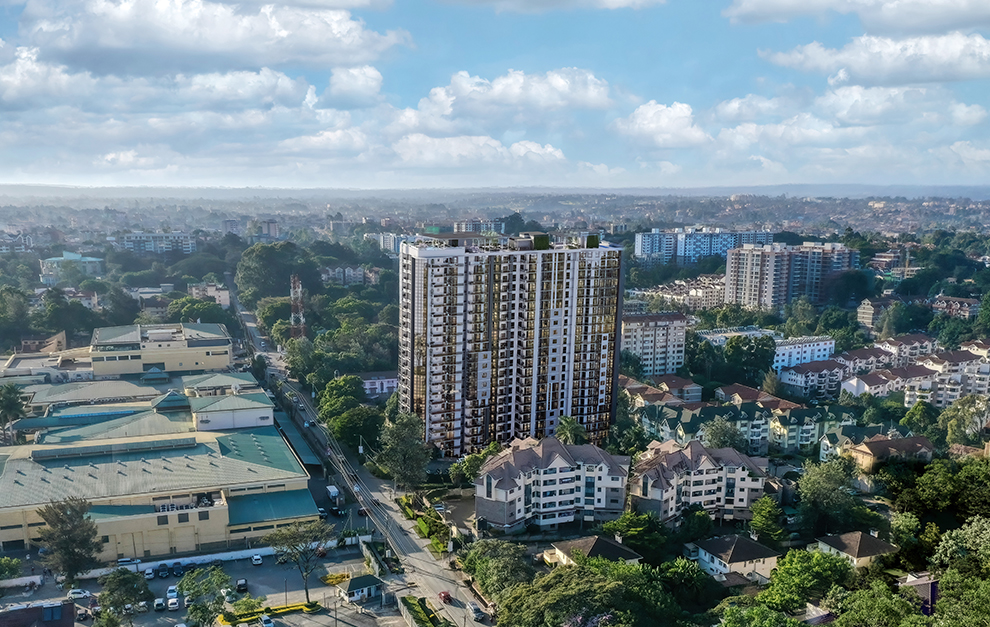
Off-plan property allows a buyer to reserve a home before construction is complete, often with payments spread across the development period. The structure can be convenient, but the buyer is committing to a future product. The developer's ability to deliver, the contract and the supporting approvals therefore matter as much as the show unit.
Before paying a booking fee or deposit, slow the process down enough to verify the project. The checks below help buyers compare opportunities without relying on projected returns, glossy renders or verbal promises.
Research the developer and project team
Review the developer's completed and active projects, the people behind the company and the consultants named for the development. Visit completed projects where possible and ask owners about build quality, communication, defect correction and the timing of ownership documents.
A long company history does not remove the need for project-specific checks. Each development may have a different landowner, financing structure, contractor and approval status.
Verify the land and approvals
Engage an independent advocate to verify the land ownership, interests or charges, permitted use and documents supporting the development. Appropriate planning, environmental and construction approvals should be reviewed by qualified professionals. The exact requirements can vary, so use advice tailored to the project.
Confirm how the buyer's unit will ultimately be identified and transferred or leased. Understand the expected ownership document, the process for its issue and any lender or third-party consents needed before completion.
Make the specification measurable
Marketing language such as premium finishes or modern appliances is open to interpretation. The agreement or attached schedules should identify the unit, approximate area, layout, finishes, fixtures, appliances, parking, store, amenities and any furniture included.
- Unit number, floor, orientation and agreed floor plan
- Measurement method and permitted variation in area
- Brands or quality standards for major finishes and appliances
- Parking and storage allocation
- Shared amenities and the conditions for their delivery
Connect payments to the contract
Understand the booking fee, deposit, instalments, final balance and any finance approval deadline. Ask what evidence of construction progress triggers each milestone and where funds are paid. Your advocate should explain the protections, risks and consequences of delay or default on either side.
Do not assume that a longer payment plan makes a unit affordable. Model the actual dates and amounts against your expected cash flow, financing terms and currency exposure where relevant.
Read the delay and change clauses
Construction programmes can change. The contract should state the target completion period, any extension provisions, notice process and remedies available. It should also explain whether the developer can change the design, materials, unit size or common areas and what happens when a change is material.
Ask how progress will be communicated and whether buyers receive scheduled site updates. Keep every update and approved variation with the transaction file.
Plan for handover and ongoing costs
Before handover, establish the inspection and snagging process, the period for correcting defects, warranties and the documents required before occupation. Confirm when service charge begins and request the proposed management budget so that the ownership cost is not a surprise.
Clarify who will manage the development, how owners participate in decisions and whether there are rules on leasing, pets, renovations or use of amenities. These rules can affect both personal use and investment plans.
Compare the finished outcome, not the render
Assess whether the location, layout, likely service charge and final specification would still make sense if expected price growth or rental income were lower than projected. Independent valuation and financial advice can help test assumptions.
Off-plan buying works best when the decision is supported by verified documents, a clear contract and a realistic budget. Browse current property opportunities, then engage your own legal and financial advisers before committing.
Find your next Nairobi property
Share your location, budget and property requirements with Kenya Classic Homes. We will help you compare current listings and arrange viewings.